TORONTO · MISSISSAUGA · THE GTA

GTA Commercial
& ICI Mortgages

Space to operate. Room to grow.

Financing for industrial, commercial and investment properties in Toronto, Mississauga and the GTA. Discuss your purchase, refinance or expansion with The Mortgage Providers.

Tell us about the property and your business or investment plans.

  • The Mortgage Providers private fund specialists
  • The Mortgage Providers fast mortgage approvals promotion

Explore your options with a GTA mortgage brokerage established in 1997.

Toronto officeServing borrowers across the GTA

Established in 1997Mortgage brokerage experience

Brokerage licence 10533Residential & commercial financing

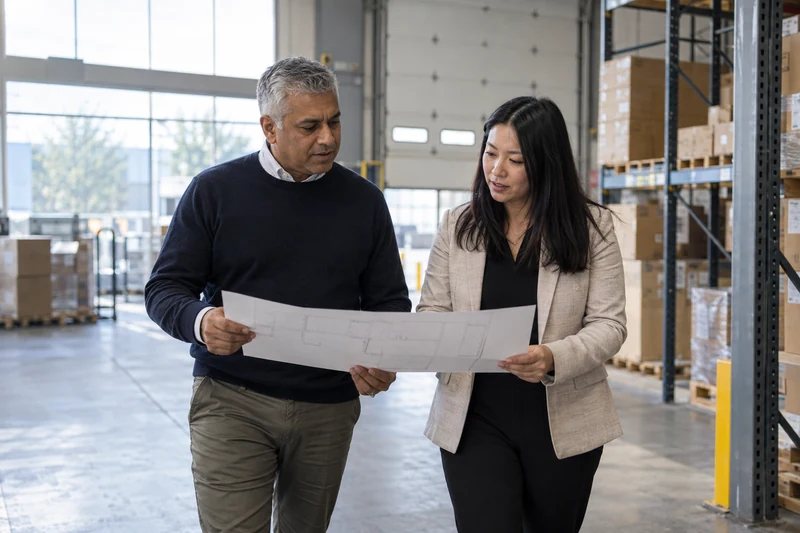
Business owner and advisor reviewing a building floor plan inside a warehouse
Connect the property’s potential with a practical financing review.

INDUSTRIAL · COMMERCIAL · INVESTMENT

Commercial & ICI financing.
Built around your property.

ICI stands for industrial, commercial and investment real estate. It covers properties such as warehouses, office buildings, retail plazas and income-producing apartment buildings. In a mortgage discussion, the term describes the property sector rather than a single loan product.

The Mortgage Providers helps GTA business owners and property investors explore commercial and ICI mortgages for purchases, refinancing and other property-related transactions. Start with the building, how it is used and the income or business operations that will support repayment.

As a mortgage brokerage, we help you review potential lender options and the requirements attached to them.

WHAT TYPE OF PROPERTY?

ICI property types.
Different requirements.

Whether you occupy the building or lease it to tenants, its use and financial performance help shape the financing review.

Industrial properties

Discuss warehouses, industrial condominium units, manufacturing facilities and distribution space. Explain the current use, whether the property is owner-occupied or leased, and any planned changes to the building or operations.

Commercial properties

Explore financing for office buildings, retail stores, plazas and professional premises. Bring details of your business operations or tenants, current occupancy and any planned fit-out or expansion work.

Investment properties

Discuss income-producing real estate, including apartment buildings, mixed-use properties and leased commercial or industrial space. Provide the rent roll, leases, operating costs and vacancy details so the review reflects the property’s actual income.

Explore store and apartment financing

MAKE THE REVIEW USEFUL

Start with the property.
Support it with numbers.

Bring the purpose of the loan, the building details and your financial information into one conversation.

  1. Define the transaction

    Share the address, price or current mortgage, amount needed and closing or maturity date. Explain whether you will occupy the property or lease it to tenants.

  2. Prepare the supporting information

    Gather business financials or property operating records, ownership details and available equity. Identify missing leases, reports or approvals early.

  3. Review the proposed terms

    Compare the payment schedule, term, amortization, fees and security requirements. Clarify any guarantees, reporting obligations or financial conditions.

  4. Plan the closing and next stage

    Confirm outstanding lender conditions, legal work and funds required to close. Consider the effect of renovations, vacancies or a future refinancing date.

YOUR COMMERCIAL & ICI MORTGAGE CHECKLIST

Bring the details
behind the building.

Start with a general enquiry. A more detailed review may require:

  • Property address, description and purchase agreement
  • Current mortgage statement and maturity date
  • Business financial statements and ownership structure
  • Rent roll, leases and property operating statements
  • Available equity and source of your contribution
  • Existing appraisal, environmental or building reports
  • Renovation plans, project budgets and approval status

Confirm the lender’s requirements before paying for new reports.

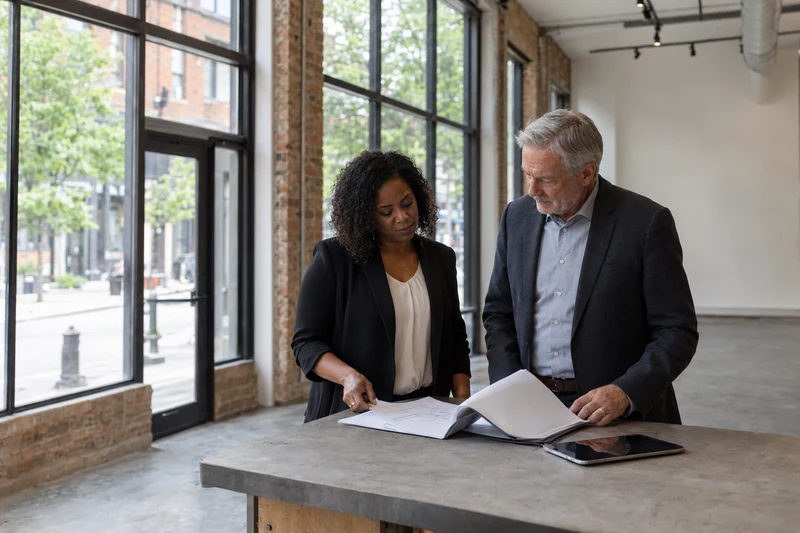
Two business partners reviewing property documents inside a vacant commercial unit
Understand the space, the costs and the next steps.

LOOK BEYOND THE INTEREST RATE

Budget for the
complete transaction.

Ask which lender, brokerage, legal, valuation and due-diligence costs apply. For a refinance, check the cost of discharging the current mortgage and the net proceeds available.

Keep property costs and operating needs in the same plan. Moving, fit-out work, repairs and downtime can require cash after the purchase closes. Confirm which expenses the proposed financing actually covers.

BDC’s commercial real estate financing overview illustrates how property funding can address different business needs. Its product terms are specific to BDC and do not describe every lender’s offer.

TORONTO · MISSISSAUGA · GTA

Start with
the exact address.

A Toronto storefront, a Mississauga industrial unit and a York Region office building raise different questions about use, occupancy and income. Share the actual property details rather than relying on a city-wide average.

The Mortgage Providers welcomes enquiries throughout Peel, York, Halton and Durham as well as Toronto. Include the municipality, property type and your intended transaction.

If conventional financing does not fit the situation, you can also ask about private mortgage funding and the costs and repayment plan it would involve.

YOUR QUESTIONS

Commercial & ICI
mortgage FAQs.

Answers about ICI properties, equity, cash flow and preparing your application.

What does ICI mean in commercial mortgage financing?

ICI stands for industrial, commercial and investment real estate. It includes properties such as warehouses, offices, retail plazas and income-producing apartment buildings. These categories can overlap: a leased warehouse is both industrial property and an investment. ICI describes the property sector, not a separate mortgage product or a guarantee of eligibility.

What is a commercial mortgage?

A commercial mortgage is financing secured against property used for business or investment purposes. The review considers the building, its use, the borrower and the cash flow supporting repayment. Requirements differ from a typical mortgage on an owner-occupied home.

What types of commercial properties can I discuss?

The Mortgage Providers welcomes enquiries about business premises, offices, retail properties, industrial buildings, warehouses, multi-unit residential buildings and development projects. Specialty properties such as hospitality or care facilities require a review of their particular operations and lender requirements.

How much down payment or equity will I need?

There is no single percentage for every commercial property. The amount depends on the proposed lender, accepted valuation, property type, financial performance and loan structure. Ask for a breakdown of your required contribution, closing costs and funds needed after closing.

What is debt service coverage?

Debt service coverage measures the income or cash flow available to meet debt payments. A lender uses its own calculation and minimum requirements. Ask which income, expense adjustments and debt obligations it includes when assessing your property or business.

Can I refinance an existing commercial property?

You can request a review of refinancing options. Provide your current mortgage balance, maturity date, property information and reason for refinancing. Compare the net funds available, repayment terms and any costs of paying out the existing loan.

Can an apartment building qualify for CMHC-insured financing?

An eligible rental building may qualify under a CMHC mortgage loan insurance program. The standard rental housing program requires at least five rental units, along with other property and borrower conditions. Unit count alone does not establish eligibility or guarantee a particular rate.

Will the lender need an appraisal or environmental report?

A lender may require an appraisal and, depending on the property, environmental or building-condition reports. Confirm the required scope, approved professionals and acceptable report dates before ordering anything. Report costs and review time should be included in your transaction plan.

Do you help with commercial mortgages across the GTA?

The Mortgage Providers welcomes commercial mortgage enquiries from Toronto, Mississauga, Brampton, Vaughan, Richmond Hill, Markham, Oakville, Burlington and Durham Region. Share the property address, intended use and financing goal to begin a review.

LET’S DISCUSS YOUR PROPERTY

Plan your next move.

Tell us where the property is and what you want to accomplish.
We’ll discuss the next step for your financing review.